Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
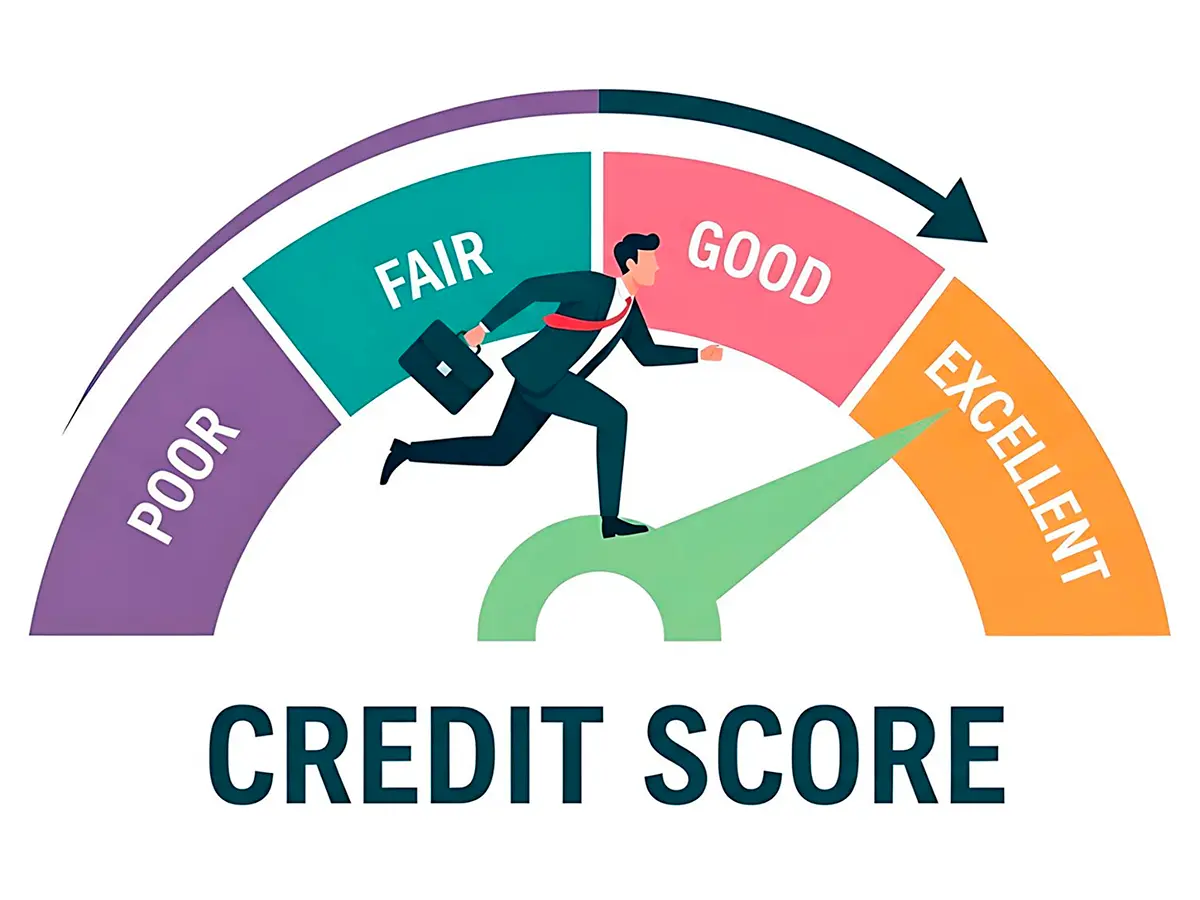
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
attorney for credit repair: clear options and safeguards
You want your credit fixed without guesswork or risky shortcuts. An attorney for credit repair gives you legal leverage, not just templates. Think of this as a market with several paths - DIY disputes, credit repair companies, and lawyers - each suited to different stakes. Your priority is safety, accuracy, and a plan that fits your timeline and risk tolerance.
What an attorney actually does
A lawyer can audit your reports, gather evidence, and press your rights under the Fair Credit Reporting Act (FCRA) and the Fair Debt Collection Practices Act (FDCPA). They draft targeted disputes, validation requests to collectors, and escalation letters to the credit bureaus. If errors persist - mixed files, identity theft marks, improper reinsertions - they can negotiate corrections, settlements, or file suit. They also advise on cease-and-desist communications, statute-of-limitations traps, and how to avoid "re-aging" a debt. Result: fewer form letters, more accountable steps.
When hiring makes sense
- Identity theft or a data-breach fallout with multiple false tradelines.
- Bureaus ignore or give canned denials after you supplied proof.
- Negative items keep reappearing after deletion (reinsertions without notice).
- Collection harassment, false balances, or threats.
- Debt buyer sues you or hints at suit.
- Mixed file (another person's data on your report) or persistent reporting after discharge or settlement.
- High-stakes timing: mortgage underwriting, security clearance, or job screening.
Realistic check: if an item is accurate and within its reporting window, no one - lawyer or otherwise - can simply "delete" it. Legal strategy shines when the issue is inaccurate, unverified, or unlawfully reported.
How lawyers compare to DIY and credit repair companies
DIY can work for simple errors: pull your reports, mark inaccuracies, dispute with documentation, calendar bureau deadlines (usually 30 - 45 days). Credit repair companies may automate disputes, but they can't litigate, and aggressive mass-disputing can backfire. An attorney adds targeted evidence, regulatory pressure, and, if needed, court action - safer for complex or time-sensitive cases.
Costs and outcomes
Fee models vary: flat fees per dispute package, hourly work for complex matters, or contingency in cases seeking damages. Some laws allow fee-shifting when you win, easing cost risk. Expect measured progress, not magic: bureaus have investigation windows, and tough cases may take multiple cycles. No one can guarantee deletions, but a lawyer can force verification, correct balances/dates, and stop unlawful collection conduct. Keep all letters, credit pulls, and phone logs organized - your paper trail is fuel.
A quick, real-life moment
You're preapproved for a refinance, then the lender freezes the file: a paid collection suddenly reports as "open." Your attorney sends a focused FCRA notice with proof of payment and an FDCPA demand to the collector. Within a cycle, the tradeline updates to paid/closed and the score rebounds enough to keep your rate lock.
How to choose safely
- Verify state licensure and a consumer-law focus.
- They ask for documents and explain your evidence gaps.
- Clear engagement letter, scope, and timelines.
- No "guaranteed deletions."
- Transparent billing; what's flat vs. hourly.
- Data security for your SSN, IDs, and bank records.
- Explains risks (e.g., waking a dormant collector) and offers a fallback plan.
Next steps
Pull all three credit reports, list every disputed item, and gather proof. Start with precise written disputes, then consult an attorney for credit repair if the stakes are high or the bureaus stall. Keep everything in writing and dated - control the process, protect your rights, and move toward a cleaner file with confidence.
San Antonio Credit Repair Attorney assists in fixing bad credit report errors and issues with debt collectors and debt buyers - J Gannon Helstowski Law ...
The Hoelke Law Firm can help you find legal solutions for your Credit Repair issue. The practice serves the San Antonio, Texas area.
Free consultations. Experienced credit repair lawyers in San Antonio, TX. Learn how to fix your credit score, and settle disputes with creditors and credit ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.